Facebook Blogging

Edward Hugh has a lively and enjoyable Facebook community where he publishes frequent breaking news economics links and short updates. If you would like to receive these updates on a regular basis and join the debate please invite Edward as a friend by clicking the Facebook link at the top of the right sidebar.

Thursday, June 2, 2011

BELLS In Hell That Don't Go Ting a Ling a Ling

After the BRICS, came the PIGS. Now a new acronym is being born, that of the BELLS. These particular "ding-dongs", however, are not a set of hollow cast-metal instruments suspended from the vertex and rung by the strokes of a clapper, they are countries, countries which may, like those unfortunate WWI British soldiers whose love of their country and sense of duty lured them into one of the most senseless conflicts of modern European history, be headed towards their own pretty unique form of modern purgatory.

The BELLS are a group of four countries (Bulgaria, Estonia, Latvia and Lithuania) who in their wisdom decided to adopt and then stick "come hell or high water" to a currency peg with to Euro. Thus was opened one of the more interesting and lively chapters in modern macroeconomic debate.

Now talk of some sort of ultimate inferno here may strike a pretty discordant note with many readers, since most of the economic chatter of recent days has centred on how the BELLS constitute a positive example, not to mention a most attractive alternative to all those dreadful sounding PIGS. According to GaveKal's François-Xavier Chauchat, for example, the BELLS should be seen as a ray of "Hope For EMU Peripherals", since just like the PIGS the BELLS have also had their own debt crisis, one which was so severe at the time that it put into question the very sustainability of their fixed exchange rate regimes. However, in these most fortunate of cases, the bad times are now well and truly behind us since a happy combination of IMF programmes and fiscal consolidation (coupled in Estonia's case with subsequent admission into the Euro group) eventually led them out of crisis, and without the need for any sort of sordid devaluation to boot. And then, as they say in Spanish "fueron felices y comieron perdices" (or to put it the English way, "they all lived happily ever after"). Or did they?

Well, on Chauchat's view, the BELL crisis was always more of a liquidity than a solvency one (see chart below) – and this despite the fact, which he notes, that Latvia was very often argued to be a modern equivalent of the Argentina of the late 1990s (an assertion which, he says, has ultimately proved to be wrong, although in fact on this particular solvency vs liquidity argument, the true test will be the ability of Latvia to pay back the 7.5 billion euro EU/IMF bailout loan, in full and on time, and especially the very onerous 2014/15 installments). From a macroeconomic perspective, however, the big issue was always one of just how the hell these countries were going to dig themselves out of the hole they had dug themselves into, and do so at the same time as staying on the peg.


A Profession That Is Losing Its Grip On Reality?

The view that the BELLS have somehow proved the monstrous regiment of professional macroeconomists totally wrong is now quite widespread (for a balanced and more nuanced version of the argument see this post by my fellow RGE Economonitor blogger Ed Dolan) , and indeed such sentiment may well form part of a much more general dispute between micro- and macroeconomists about how to find solutions to the present crisis. Only last week the Latvian Prime Minister Valdis Dombrovskis presented a book in Riga which he has co-authored with Anders Åslund of the Peterson Institute which has the rather assertive title: How Latvia Came through the Financial Crisis. The associated press release proudly states that a key lesson to be learnt from the resolution of Latvia’s financial crisis is that "devaluation is neither the panacea nor the necessity that many economists make it out to be".

Not content with this statement our authors go even further, striking what some might consider to be a rather too "close up and personal" tone:

"Finally, the international macroeconomic discussion was not useful but even harmful. Whenever a crisis erupts anywhere in the world, a choir of famous international economists proclaim that it is “exactly” like some other recent crisis—the worse the crisis, the more popular the parallel. Soon, prominent economists led by New York Times columnist Paul Krugman claimed that “Latvia is the new Argentina.” A fundamental problem is their reliance on a brief list of “stylized facts,” never bothering to find out the facts".

As a macroeconomist who has been deeply involved in the Latvian debate I have to say that if such statements weren't so foolish (and ill-befitting of the Prime Minister of any country) I would want to protest that they were extraordinarily condescending and even verging on being insulting. As someone who has spent hours and hours during this crisis perusing excel sheets and making charts trying to fathom what is going on in the BELLS (and in particular in Latvia) I have to say I certainly don't recognise myself in this paragraph, and if anyone could be bothered to take a look at that infamous Krugman piece they would find he was basing his argument not on some obscure set of stylised facts, but on my detailed analysis of the problem (right or wrong, but here it is - why the imf's decision to agree a Latvian bailout programme without devaluation is a mistake).

The funny thing is that, far from having learnt from the error of my ways, I still consider the original IMF decision to have been a mistake, although I would point out that I personally never suggested Latvia was like Argentina (another thing is to say that much of what is going on along Europe's periphery of late carries with it a distinct sense of Argentina deja vu), since I actually think that Argentina is an example of what not to do and that if you are looking for historical precedent for what should be going on in Latvia (read the BELLS) Turkey would be a much better role model. I also think that one of the conclusions we will eventually be able to draw from this whole sorry affair is that those who specialism is not macroeconomics would do better dedicating more of their precious time to trying to understand what we are saying rather than engaging in ill-informed ideological polemic. And I say this since I believe that the Latvians themselves deserve better. They may well not be able to avoid serving as guinea pigs, enabling macro- and microeconomists to see just who is right, but they surely don't merit being converted into yet another ideological football. Didn't we have enough of that during the Soviet years!

On the other hand, and before getting into the actual analysis, I want to stress that I personally am not advocating devaluation of the Lat at this point in time. Even though I still consider it a mistake not to have devalued, and an even bigger mistake on the part of the EU leadership not to have accepted the IMF proposal for immediate devaluation and Euro entry, I accept that the decision not to devalue represented the democratic will of the Latvian people (following the advice of the IMF given the EU response), and it was for precisely this reason that I declined to go to Latvian in August 2009 and speak at a meeting organised by the then governing People's Party, since I think I was only being asked to go there to cause trouble.

The difficult thing here is not to cause trouble (which is easy) but to find realistic solutions, which is why we need free and open debate.

Did Latvia's Internal Devaluation Cut Hard Enough And Deep Enough?

The point, I think, is this: if Latvia is not going to recover the competitiveness all agree it lost through a normal devaluation process (for whatever reason) then it needs to do so via the procedure which has become known as "internal devaluation" (a procedure which in an earlier era was known by the name of "wage and price deflation"), and indeed this is what the Latvians have attempted to do.

So the question now is has this worked? Or put another way, has the internal devaluation gone far enough and deep enough? The conventional wisdom has it that it has, but I, for one, am not convinced, and looking at the latest round of Latvian data serious questions arise as to whether the recovery is strong enough or sustainable in the longer term.

Growth started to return to these economies in the second half of 2010, but with capital inflows now well below pre-crisis levels they have now entered a lengthy and difficult adjustment process. With domestic demand well below earlier highs and still struggling, exports have now become the prime mover of economic growth. Since the recovery in external demand has produced a rapid return to earlier export peaks the impression of a return to earlier economic dynamism has been created. I think this interpretation of the recent strong export growth is misleading, since it is one thing to recover lost ground, and quite another to attract the FDI needed to seriously expand capacity and keep increasing exports beyond their pre crisis peak. Strong year-on-year increases in exports have moved headline GDP numbers forward, but as 2011 continues annual export growth rates will drop substantially, and may even get stuck at a snail’s pace, meaning that the respective economies will be struggling to find growth, create jobs, and maintain the servicing of their external debt.

The most worrying piece of evidence I have found is the failure of capital investment to rebound alongside exports. In part this is understandable, since a lot of the earlier capital investment was in property, but this offers only part of the explanation, since for these economies to really take off as export driven strong new investment growth in plant and equipment will be needed. In order for these economies to attract investment in sufficient volume they will need to recover a large part of the competitiveness lost between 2005 and 2008, when wage growth far outpaced productivity gains. However, given the difficulties faced in lowering the exchange rate, they can only realistically try to recover lost ground through sustained productivity improvements, a lengthy and slow process, and in the meantime the debt and population ageing problems keep ticking away

In my opinion, and despite some early encouraging signs, it is far from self-evident that the so called “BELLS” (Bulgaria, Estonia, Latvia and Lithuania) are going to be able to export their way out of trouble in the way they need to (given the collapse of internal demand) with the current relative price structure. It is my considered opinion that the “internal devaluation” process may have been underambitious and allowed to come to a halt far too soon. And indeed, if we get to the point, this is why so much of the conventional macroeconomic wisdom and advice leans towards open devaluation, simply because it is hard to maintain the political consensus for long enough to carry out a deep and painful deflation adjustment, and indeed this is the lesson drawn from the 1930s that I was brought up on.

Export Dependency and An Ageing Workforce

In addition two major unresolved issues may leave a legacy, one which could weigh down any recovery and lead to more serious problems when the next recession eventually arrives. Many observers seem to forget that it is one thing navigating a leaky ship when you have the wind behind you, and quite another one going face-forward into a tempest.

In particular there are two things which preoccupy me about the present situation:

a) The existence of a substantial debt overhang the credit crunch which exists as a result
b) The demographic challenges the country faces, and in particular the impact of a rapidly ageing and declining population.


But before getting into this, let's take a serious look at the current state of play in the Latvian game.

Worrying Signs In Latvia

The first thing I notice when I start to go through the Latvian data is that despite a substantial improvement in exports:

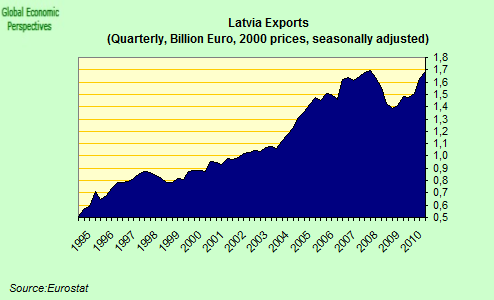


GDP growth is currently slowing.


Latvian GDP expanded by a quarterly 1.5% in Q3 2010, by 0.9% in Q4 and by 0.2% in Q1 2011. Thus Latvian GDP has been steadily slowing, and this despite the fact that the export environment in the first three months of this year was exceptionally positive, and Latvian exports were booming. Latvian GDP fell by around 25% during the crisis, and has subsequently rebounded by 5% (over 5 quarters). We are far from a "V" shaped recovery, and pardon me if I mention it, but it is precisely the sort of thing most macroeconomists were imagining would happen.

Essentially the problem is that consumer demand has failed to recover, and if my analysis (about ageing and the debt overhang) is right then it will continue to fail to recover (all of this, incidentally, is what I argued would happen after the crisis broke out).


Industrial output languishes (partly because the non-tradeable sector is contracting as fast as the tradeable one is expanding).


While capital investment fails to recover:


Obviously a large part of the investment slump is due to the decline in consumption activity, but there is little sign of a serious pick-up in ex-construction investment, and anyway, outside of construction there was comparatively little investment going on in the period before the bust, and very little FDI.


So Where Is The Problem?

Basically the Latvian economy faces three main problems

i) a debt overhang
ii) a declining and ageing population
iii) a high level of unemployment, low rate of job creation, and a substantial wage differential with Western Europe which encourages young people to emigrate and drift west.

The first two problems put a serious brake on economic growth, and it is this that exacerbates the third problem, which then in its turn feeds back and aggravates the first two.

Cheap interest rates, supported by the peg and the prospect of Euro membership meant that Latvian households and corporates were able to get themselves heavily into debt. And debt in Euros (which is why the devaluation difficulty exists) - over 85% of Latvian mortgages are Euro denominated.


Now the Latvian economy is experiencing a sharp credit crunch, private sector credit which was increasing in 2007 at a rate of around 65% is now falling at a rate of 9% per annum.


Has The "Internal Devaluation" Been Called To A Halt Too Soon?

Claims that Latvia's internal devaluation has been deep and effective are widespread.The following claim from Commerzbank's Barbara Nestor is typical:

"The competitiveness adjustment has been substantial; labour costs fell 25% from the peak. The gap that opened up between productivity growth and labour costs in the boom years has already been closed. Exports responded sharply. Resources have not been switched among sectors, but production has been redirected from domestic use to exports".

The IMF itself is also pretty congratulatory. In this months press release announcing completition of the fourth review of the standby arrangement they state:

"Strong policy actions under the SBA have helped restore confidence, contributed to economic recovery, and enabled significant progress toward Latvia’s goal of euro adoption. The government has continued to achieve substantial fiscal savings while also protecting the poorest through social safety net spending and a temporary public works jobs program, and is strengthening its active labor market policy efforts. Looking ahead, the government has committed to meet the Maastricht criteria for euro adoption and strengthen the financial sector, which should further enhance confidence and support a rebound in growth".

Or again in the joint IMF/EC Statement on Latvia on the Review Mission:

The Latvian economy is now showing clear signs of recovery, with economic growth of 3.3 percent expected this year, reflecting the Latvian authorities’ continued implementation of their economic program. Their policy agenda for 2011 sets the stage for meeting the conditions for euro adoption in January 2014, and for sustaining the economic recovery

But is the Latvian economy showing clear and unequivocal signs of recovery? This is exactly the question I am asking here. Part of the issue is whether the competitiveness correction has so far been deep enough to ensure a higher level of competitiveness in the non-tradeable sectorer and a shift of resources from non-tradeable to tradeable. Certainly when the IMF programme was being contemplated, the extent of the correction needed and the difficult challenge which implementing it would involve was not doubted by anyone. Here's what the IMF had to say at the time of the staff report on the standby facility request (IMF emphasis):

In addition to maintaining the existing fixed (narrow-band) exchange rate, staff considered a number of alternative exchange rate options. These included, inter alia: (i) widening the current exchange rate bands to the full 15 percent range permitted under ERM2; and (ii) accelerated euro adoption at a depreciated exchange rate.

The main advantage of widening the bands is that it should eventually deliver a faster economic recovery. Although growth would be depressed in the short run by balance sheet effects, the economy might then bounce back more sharply, and a Vshaped recovery would likely start in 2010. This reflects a faster improvement in competitiveness since high pass-through (reflecting Latvia’s openness to trade and liberalized movement of labor within the European Union) would be dampened by the negative output gap. Enhanced competitiveness would also reduce the current account deficit more quickly. This would come mainly from import compression, with a relatively slow response of Latvia’s underdeveloped export sector, especially as the external environment is not as supportive as in previous devaluation-induced recoveries as Argentina, Russia or East Asia.

So at the time a 15% exchange rate adjustment was being contemplated. Did we get that? Well I personally don't think so. If we look at the CPI, the drop (from peak to trough) is only something like 3%.


In fact the producer price index fell a little further, maybe by about 12%.


But as can be seen, in both the CPI and the PPI case, since these indexes bottomed prices are now rising again. And indeed they are rising faster than is the case in those countries with which the Latvian currency is pegged (the Eurozone 17).


So in fact, and especially if we take as a point of reference the start of 2007, we can see that the actual price correction has been comparatively small, and indeed the position is once more deteriorating, even though output in the Latvian economy is over 20% below its pre-crisis peak. Is that really such a flexible situation?

A similar pattern emerges if we look at wage costs and productivity.


As we can see, despite having a relatively high standard of living Germany has managed to maintain unit labour costs relatively stationary over the last decade, due to rising productivity. Latvia evidently has not. This has nothing to do with being rich or poor, as can be seen from the years 2000 to 2004 Latvian living standards were rising, but they were rising in line with productivity, which is of course perfectly sustainable, and basically the pattern you want to see. Then from 2005 onwards the link was broken, and Latvian wages exploded in a way which was totally unsustainable. During 2008 and 2009 unit labour costs started to improve (in part because a lot of very unproductive workers in construction lost their jobs, the pattern in Spain is similar) but from the start of 2010 onwards the process has been in reverse gear again, and once more it is interesting to note that German labour costs (even though the economy is booming) are not following suit.

A lot of ink has been spilt writing about the large drop in wages in the public sector (possibly over 20%) but unfortunately public sector workers normally don't export, and if we come to look at private sector wages, and especially hourly wage rates, then we again find that the correction has not exactly been massive, and of course, inter-annual wage rates are once more starting to rise.


The rough and ready measure most macroeconomists like to use when it comes to competitiveness changes if the Real Effective Exchange Rate, and as we can see from the chart below, the loss of competitiveness (when compared in this case with Finland) since 2005 has been substantial. But then when we use REERs most people who really aren't that convinced that exchange rates matter tend to be not very impressed.


So let's try and put the argument another way. The real proof of the pudding is in the eating, and the real test of Latvian competitiveness is whether, now that it is totally export dependent, the Latvian economy will be able to produce sufficient economic growth and employment such that the weight of the debt can be steadily burnt down. And let us remember here the currency pegger's (or euro member's) catch 22: growth in nominal GDP is what matters when it comes to reducing debt, and nominal GDP is composed of real growth and inflation, so in a way inflation could be beneficial, but any inflation you have which is over the level of your countries of reference (the Euro Area 17) will lose you competitiveness in a way which reduces real growth, so you are up against a limit on both sides (deflation, which makes you more competitive, only compounds the debt problem) and possible the most appropriate characterisation of the situation would be "trapped".

The real problem now is that the credit-bust economies are totally export dependent for growth. What does this mean. Well let's take this simple and rough-and-ready expression:

GDP = Domestic Consumption + Investment + Government Spending + Net Trade

(Growth in Net Trade = Growth In Exports – Growth in Imports)

Which means growth in GDP = Growth in the sum of the above factors. Now we know that domestic consumption is in decline, and that investment in plant and equipment will only return in statistically interesting volumes to meet the needs of export growth. We also know that government spending is being reduced (that is what the IMF programme is centered on), so all we are left with for a real growth driver is exports.

But when we come to look at the SIZE of the Latvian export sector, we will see it is way to small for the job. The chart below comes from national accounts published by the Latvian statistics office, it shows GDP and value added in manufacturing industry. I think it is obvious that the proportion here is horribly small (only slightly over 10%), since even though Baltic economies generally are fairly open, many of the exports are in fact imports that have been reprocessed so actual proportion of their value produced in the country is not large. Germany by comparison (which is a modern economy, with reasonable living standards) has over 40% of GDP originating in value added in manufacturing. Yet this tiny part of the Latvian economy is now about to do the heavy lifting? It just doesn't make sense. Nor does it make sense that the IMF focus so much attention on reducing the fiscal deficit and virtually none on this issue, yet it is on resolving this issue that Latvia's economic future belongs.


There is another piece of evidence that Latvia's internal devaluation has eased up far to soon, and this comes from the current account. A great deal of praise was lauded on Latvia for the rapidity with which the current account went into surplus. In part this was the "ouch" effect, as financing dried up, people lost their jobs, and imports fell sharply. Exports, as we have seen, also improved, and this certainly helped. But there was another factor which we should also take into account, and that was what happened to the income account. This is composed of interest payments and returned profits and dividends. Now Latvia has a net external debt of not far short of 100% of GDP, and this involves a lot of interest payment. As is well known, most of this debt is denominated in Euros, and attached to Euribor interest rates, so of course, as the ECB brought rates down, interest payments came down in like fashion. At the same time, as the economy was contracting by 25% firms were producing a lot less in the way of profits, and there were far fewer dividends.

Now things are improving again, and as we can see in the chart below, the current account is once more moving back towards deficit. This is not a good sign.


So there we are, these are my causes of concern, and I think it is now over to those who already feel that the devaluation debate has been shown to be irrelevant to suggest what they think should be done next to put Latvia back on the "internal devaluation" track again. When I suggested at the start of this post that Latvia might be stuck in a peculiar kind of hell, possibly limbo would be a better term. Latvia's current situation is hardly comfortable. Unemployment is still very high, and new employment is only arriving in a trickle. Meantime the debts are still there, and the problems people are having paying them haven't gone away. In this sense a "restructuring bomb" is still ticking away under Latvia, and rather than continually crying victory maybe it would be better if more people (Prime Ministers included) dedicated a little more of their energy to trying to defuse it.


This post first appeared on my Roubini Global Econmonitor Blog "Don't Shoot The Messenger".

Sunday, January 9, 2011

And Then There Were Seventeen....

"If you know your Thucydides and the Melian dialogue you know that small countries rely most on everyone following the rules. That's why we follow the rules. If there are no rules, then the big will do what they want,"
Estonian President Toomas Ilves in an interview with the EUobserver

In a blog post which has gathered a certain notoriety, Paul Krugman recently sent the Estonians his condolences. I will send them, not my condolences, but my congratulations, and these not for the somewhat dubious honour of being allowed to join the Eurozone, or even for having carried out a highly successful "internal devaluation" (this outcome is still in doubt), but rather for their stubborness, courage and tenacity. These are indeed hard (and enduring) men and women. And in honour of their courage I offer them a homage, in the form of two charts. The first of these is the latest Estonian industrial production one.


While the second is the Spanish equivalent.


Can you spot the difference? If not squint a little closer. Estonia's economy fell by around 18% during the crisis, while Spain's has so far has fallen only by something like 7%, yet Estonia's industrial output is now almost back to where it was before the crisis started, while Spain's has fallen but so far not recovered. No sign of even the tiniest green shoot.

Curiously, Spain's political leaders constantly complain that the markets are being unfair to their country, and are underestimating their ability and determination in responding to the crisis, yet if we compare the relative performances of the industrial sectors in the two countries, it is pretty obvious why the markets entertain the doubts they do. Both are destined now to live from exports, but one country is evidently living rather better from them than the other. It is clear that companies in the Estonian industrial sector have been far more agile in diversifing and finding new markets than have their Spanish counterparts.

Both countries experienced a construction lead "boom-bust" (Spain's of rather larger proportions than the Estonian one), and consequently now face highly impaired domestic demand, yet the Estonians have succeeded where the Spaniards have failed, by shifting a part of their previously inwardlooking industrial base towards the outside world and towards growth. There is simply no other explanation for the evident discrepancy, since (as we will see below) Estonia's industry is not growing due to the pull of domestic demand, although it is on the point of returning to "back to normal" operating levels. Spain's export sector is also recovering (after all the external demand is now there), but the part of Spain's industry which is geared towards supplying domestic demand simply hasn't been able to adapt, and is still contracting along with domestic consumption. In fact it is still contracting so rapidly that that the shrinkage is totally cancelling out all the fine work being done by the companies who are doing all the exporting, which is why industrial output remains more or less stationary, and the Spanish economy fails to return to life.

Many Rivers Left To Cross

Well that, as they say, was the good news. What follows possibly won't be anything like so palatable for Estonians to read as what went before, which doesn't mean it isn't worth reading and thinking about. You see, that old black magic (sorry, devaluation) debate, was never about whether or not the Estonian export sector could recover to its old level after the economic contraction came to a halt. As I keep stressing, it is obvious that it could, since in this case recovery depends on factors external to Estonia, and these factors have now changed, as a number of countries have seriously started to recover. No, the issue was always about the fact that the Estonian economy had become severely distorted during the boom years, and that the existing export sector was too small to do the heavy lifting that was going to be required of it after the bust in domestic demand. How many times did people say to me during those early days "but what can we export?", or "don't you realise that Estonian exports are largely re-exports of processed imported goods", as if these added disadvantages made the situation any easier, or my arguments somehow irrelevant. When a country is in trouble, but really in trouble, one of the first signs, I reckon, of the depth of the problem is that you get a long queue of official economists lining up to give you a thousand and one reasons why it is going to be impossible to export your way out of difficulty. This is like a leading indicator for "problems looming", since the situation has become so serious that effective solutions are virtually beyond the realm of the thinkable, and we need to soothe ourselves with nice sounding palliatives. In the realm of economic science, however, reality has a nasty habit of coming back and waking us from our slumbers.

What all this really suggests to me is that the thrust of the original argument about why the size of the export sector needs to increase sharply in economnies which have become so badly distorted as the Estonian and Spanish ones have was never really properly understood. So it is in honour of all those valiant Estonians who have sacrificed so much in order to gain so little that I endeavor just one more time to make things clear (my original pieces on Estonia's internal devaluation can be found here and here).

The Estonian Economy Is Recovering!

As one-commentator-after-another never tires of informing us, the Estonian economy has returned to some sort of growth recently, indeed (hat tip to Krugman) the Washington Post even went so far as to lump it together with Germany as one of Europe's “growing economies”, while the Economist Central Europe correspondent described it as a Nordic Kitten, seemingly a designation created to distance it from its more problematic Baltic neighbours. Unfortunately, wine doesn't improve simply by changing the label on the bottle (even if it does now say “appellation Frankfurt controlé”), and Estonia is neither a growth economy (which is the Goldman Sachs term for the new Emerging Market tigers like India, Indonesia, Turkey and Brazil) nor is it a "growing one", it is simply a "steadily recovering" one, and what's more, given the severity of the challenges it still faces it is far from having entirely managed to distance itself from the set of economic problems characteristic of what has come to be known as the “Baltic syndrome”.

Yes, Estonia’s economy has now started to grow again, indeed it was up by an annual 5% in the third quarter. But, to put this number in context, it was still down by around 16% from the Q4 2007 high, and just below the level of Q3 2005. So there is still rather a long way to go to get back to meaningful growth, indeed so long, as Krugman again points out, that IMF forecasts don't contemplate the country's economy reaching its 2007 level again before 2015 (Germany just more-or-less hit its 2007 level in 2010).


So, what is slowing the recovery down? Well, as I indicated at the start of this post, it certainly isn't the industries in the country's export sector, which are now more or less back to where they were before the crisis started.


But rather the problem lies in the state of private domestic demand, which obviously isn’t recovering.


As the Estonian Central Bank put it in their economicpolicy statements (and here, and here) on the latest GDP numbers:
“Estonia's recovery has been mostly driven by exports, which, measured in current prices, reached close to the all-time high in September”, and “Export growth indicates that the economic activity of our main export partners is expanding quickly and Estonia's companies are making good use of it.... The export volume of industrial production reached a historical high in the third quarter. Irrespective of the continuously weak domestic demand, the sale of industrial production started to pick up in the domestic market as well, but it is still some 25% below the pre-crisis level.... since unemployment continues to be high, the level of consumers' income and purchasing power will remain weak in the next years”.
And as the central bank also point out, export growth will now be harder (that is we have now picked most of the low lying fruit).
“Though most of industrial enterprises still have under-utilised production capacity, the existing capacity stock is running out along with rapidly expanding sales volumes. This refers to the need for additional investment”.
Yet, unfortunately, the sad truth is that investment activity has still not picked up.


This lack of series investment in fixed capital contrasts sharply with recent movements on the equities side, since, according to Bloomberg data, Estonian stocks are valued at an average of 16 times estimated earnings, compared with 11.3 times for Polish and Czech shares, and 12.6 times for Slovenia (the chart sort of resembles the export one, doesn't it?).


But the issue is this: following a pattern seen in many emerging markets over the last 12 months, short-term fund inflows pushed values on the Tallinn exchange up by some 73% in 2010, making it the third-best performance worldwide, according to Bloomberg data. They also quote Tallinn-based SEB researcher Peeter Koppel as saying: “Euro adoption has somehow triggered more widespread thinking about saving and investing in general,”...... Foreign retail investors “now have the hard fact of euro and the certain caution, especially from the Scandinavian side, is gone.” Which sounds to me more like “previously wary investors have now thrown caution to the wind,” on the back of all the pro-Euro Nordic-kitten hype. What Estonia needs, and is not getting (as the central bank itself recognises) is serious, long term, FDI for greenfield projects generating jobs and output in the export sector.

Boosting Domestic Demand Means Increasing The Size of the Export Sector & Creating Employment

As I say, in contrast to what is happening in the external sector domestic demand is far from recovering. Retail sales were up 5% (at constant prices) in November over November 2009, and 1% in October. But the annual rise is more a by-product of the very low level of sales hit in November last year, and in fact between January and November 2010, retail sales were down 4% compared to the same period in 2009.


The domestic construction sector isn’t recovering either. According to Statistics Estonia, the total production of Estonian construction enterprises increased 1.2% in Q3 2010 compared with a year earlier. But when you read the fine print, the increase was entirely produced by construction companies operating abroad (whose activity was up by 25%) – ie once more it is a question of exports.


And in fact construction output inside Estonia fell by around 1% compared to the 3rd quarter of 2009, and even this drop only wasn’t larger due to the availability of EU infrastructure funding, since the volume of building construction decreased 9% while the volume of civil engineering increased 15% at constant prices. According to data from the Estonian Register of Construction Works, in the 3rd quarter of 2010 there were only 481 housing units completed - 50% down on the same period of 2009. 65% of these were flats, the majority majority of them in Tallinn.

As the Central Bank point out, domestic demand can only improve in a sustained way if there is a major improvement in the labour market, but as they also stress, this is only recovering slowly, with the unemployment rate declining to 15.5% in the third quarter, and with the need to improve productivity and only low growth expected in the quarters to come, unemployment is likely to remain high for several years.


So despite the recovery in external demand, as was to be expected the demand for domestic credit far from recovering continues to contract, whether we are talking about corporates:


or about households:


or about housing mortgages:


Added to this, the way that fiscal austerity was implemented (raising VAT, and fuel costs) has meant that the Estonian price level, far from continuing to deflate (which is what is needed to increase competitiveness quickly enough) is now rising again, and at around 5.5% (my estimated HICP, the Estonian CPI was up 5.7% but the weightings are different) is well above the 2.2% estimate for the Euro Area, or the 1.9% December inflation estimated for Germany by the Federal Statistics Office. Perhaps one of the clearest indications of the malfunctioning of the Eurozone as currently structured is that the Germany economy (which is recovering rapidly) is experiencing far higher levels of inflation than the Eurozone periphery, which in theory should be deflating to recover competitiveness.


True Estonia did begin to recover some part of the lost competitiveness, and unit labour costs as compared with some key competitors did start to improve, but this process slowed considerably in the first two quarters of 2010, marked time in the third one, and may actually have started to deteriorate again in the final quarter as inflation accelerates (OECD data - please click on image for better viewing).


Hourly wages (on a moving average basis) seem to have stopped falling, and the next move will almost certainly be up as inflation bites in.


True, the Central Bank would undoubtedly argue that much of the inflation was due to food and energy, and that core inflation was running much lower (1.2% in November), but it is hard to see the impact of movements in the leading CPI not feeding through into wages, and producer prices (another important measure of industrial costs) were up an annual 4.5% in November.


And Its A Hard Road To Travel!

In his most recent assessment of the Estonian situation (Toughing It Out: How the Baltics Defied Predictions) Christof Rosenberg (former coordinator of the IMF baltic intervention, and current head of the Fund's Hungary mission - this man also likes hard challenges!) also pays hommage to the grit and flexibility of the Baltic populations (a characteristic I also wholeheartedly applaud), but he draws a conclusion which I feel is as yet at best premature.

"The Baltic experience demonstrates that large economic adjustment, including nominal wage and benefit cuts, is indeed possible under a currency peg (or, for that matter, in a currency union)".


Certainly, as Christoff points out, a large correction has taken place in Estonia. The current account, for example, is now in surplus.


The issues I am raising is whether this correction is enough, or whether it is sustainable. As the Bank of Estonia note, the Non-performing loans situation has been stabilised, and the value of loans overdue for more than 60 days contracted by over 250 million kroons in November to stand at 6.8 per cent of the total loan portfolio. But most of the old loans are still there, they have not been cleaned from the books, and have been sustained and refinanced by what Christoff calls the "deep pockets" of the Scandinavian lenders. These loans would be once more put into question by any renewal of the internal devaluation and serious price deflation. So hard decisions are going to need to be taken.

Inflation is already excessive, and net-exports are nowhere near large enough as a proportion of GDP to carry the economy forwardwith a strong growth dynamic. Thus, I think it is very true to say, as Christof does, that it still far too early to pass any kind of definitive judgement on the success of what he calls "the Baltic strategy". There is still a very long hard road out there in front, and the hardest and steepest part may well be yet to come.

Monday, October 11, 2010

Estonia's Now-You-See-Me Now-You-Don't Inflation Rate

Just to follow up on my recent long Estonia post, a couple of new data points have caught my attention recently: the sharp rise in Estonian inflation and the ongoing goods trade deficit.

In the first place it is worth noting that Estonia's trade deficit went UP again in August. Of course, the countries ongoing services surplus takes some of the edge off, by, since Estonia is now an export driven economy, to return to stable growth and create that much needed employment Estonia needs a trade surplus, not a deficit. Of course, the headline catcher is that August's export were up 37% over August 2009. The number looks a little less impressive when you notice that imports were also up by 34%, and take in that a significant proportion of exports are imports which are re-exported, and then you look at the chart (below) and see that both are still running at levels well below their pre crisis peaks.


To add insult to injury, despite the rapid export rise, Augusts trade deficit - some 71 million euros - actually increased slightly when compared to August of the previous year.


And here's the smoking gun which can help us understand why, despite the legendary "internal devaluation, the underlying Estonian trade deficit continues: the ongoing surge in inflation, itself in large part a by-product of the tax increases and energy subsidy reductions made to keep the fiscal deficit under control .

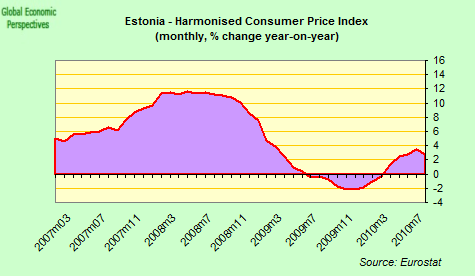
According to Statistics Estonia, the consumer price index was up by an annual 4.0% in September, and by 0.8% when compared to August this year. Goods were up 4.5% and services 3.0%. Food prices were part of the problem, since they were up 7.0%. But, as the statistics office report informs us, government administered prices of goods and services were up by 8.1% while non-regulated prices were only up by 2.7% - that's the giveway datapoint, I think.

Two fifths of the inflation was the result of a 6.6% price increase in food and non-alcoholic beverages, but the 10.2% price increase of electricity, heat energy and fuels accounted for 25% of the total, and the 8.2% excise duty induced price increase in alcoholic beverages and tobacco also had a significant impact on the consumer price index.

So inflation is rising, but even worse, so too are inflation expectations.
Inflation expectations by Estonian consumers continued to rise in September, according to Konjunktuuriinstituut, an economic research institute in Tallinn. The outlook is “certainly” affected by the prospect of euro adoption, the institute said.

Thirty-five percent of consumers polled by the institute this month expect inflation to accelerate in the next 12 months, compared with 32 percent in August, and 5 percent a year earlier, it said.


So, if those taking the policy decisions aren't careful Estonia may be about to loose its "poster boy" image, and find itself added to the ranks of the "fallen angels". The above comparison of Euro Area 16 and Estonia CPI inflation makes it look awfully like the timing of the tax and subsidy changes was calculated to get good inflation readings during the key euro decision window. It is hard to believe that neither the central bank nor the ECB couldn't see the current surge coming - or if they couldn't, then the best you could say is that they were extraordinarily incompetent in their handling of the issue. And if you look at the competitiveness loss the price index reveals since the start of 2007 (even) the short period of deflation has nowhere near compensated for it, and the current price surge will soon eat it what little competitiveness improvement there has been all away.

Of course, the central bank has expressed some concern, “There is a threat the present price and wage levels will not sufficiently support new investment and job creation,” it said in its latest economic report, although it stressed that it considered the increase in ongoinginflation due to rising food prices is likely to be temporary.

All of which only confirms my impression that the Estonia entry decision was made in haste, coinciding as it did with May's sovereign debt crisis. The decision was a kind of vote of confidence in the resilience of the Euro Area: "look, we aren't about to fall apart, we're even accepting new members". In fact ECB President Jean-Claude Trichet almost said as much on a recent visit to Tallinin. Europe's economic and monetary union is committed to accepting further members, he stressed. "The euro area is not a closed shop," M. Trichet said, while attending a festive event to celebrate Estonia's upcoming accession to the eurozone. Rather, he said, it is open to any country "that fulfills any of the preconditions in a sustainable manner."

The keyword here is "sustainable". As reported on this blog, there were those within the ECB, and most notably ECB executive director Juergen Stark, who opposed the decision, by simply arguing that, in the light of Greece's inability to endure the discipline of EMU membership, future applicants should be screened more tightly. In the past, membership had rested on the ability to conform with numerical targets on inflation, public debt and exchange rate at a specific point in time. Stark spoke of the need for countries to demonstrate that their compliance with the entry criteria is sustainable beyond the snapshot moment. As we can see, at least in terms of inflation, it is very hard to argue that Estonia's economic performance is.

Jean-Claude Trichet also took advantage of his visit to stress that Estonia must remain “alert” on price developments and take “forceful” action to stem inflation after joining the euro-region economy. But, understandably, Prime Minister Andrus Andrip replied that Estonia is now going to have relatively “few tools” to control price increases. The main technique available is to run a fiscal surplus to drain demand, but with an economy which is suffering from the level of output loss that Estonia's is this is hardly contemplateable.

Basically it would have been much more advisable to resolve these issues before joining the euro, but now it is a little late for that, so, who knows, maybe Estonia will eventually become the first candidate for the recently proposed EU imbalances surveillance mechanism.

As the press release puts it: "The global economic and financial crises, followed by the so-called debt crisis, exposed the need for reinforced economic governance in the Economic and Monetary Union (EMU). Economic policies need to be better co-ordinated and surveillance enhanced".

"Surveillance would start with an alert mechanism that aims at identifying Member States with potentially problematic levels of macroeconomic imbalances. The alert mechanism would consist of a scoreboard complemented by expert analysis".

"The scoreboard would be composed of a set of indicators in order to identify timely imbalances emerging in different parts of the economy. The set of indicators should be sufficiently large to cover any possible case of major imbalance and making sure that it is sufficiently sensitive to detect imbalances early on. Possible indicators would most likely include both external (e.g. current accounts, real effective exchange rates) and internal ones (e.g. private and public sector debt). The composition of the scoreboard may evolve over time due to changing threats to macroeconomic stability or advances in data availability".

"Alert thresholds would be defined and announced for each indicator. The thresholds should be seen as indicative values which would guide the assessment but should not be interpreted in a mechanical way. They should be complemented by economic judgment and country-specific expertise".

But looking at that rising inflation profile, and thinking of Prime Minister Ansips statement that the country has few tools left with which to tackle the problem, whoever would have thought that just a few short years ago Lithuania had its application to join the Euro turned down simply because its inflation wasn't considered to be sufficiently under control. My, my, how things change.
On account of its 2.63% March 2006 inflation, Lithuania has for now failed to qualify for the euro zone, while Slovenia is all set to adopt the euro in January 2007.

Lithuania meets all the criteria for the adoption of the common European currency, except for the one on inflation. The Baltic state's latest inflation figure is only marginally higher than the 2.60% benchmark applied by the Commission and the European Central Bank to decide whether a country is fit to adopt the common European currency.

According to Monetary Affairs Commissioner Joaquin Almunia, the criteria, laid down in the EU's Stability and Growth Pact, are there to be rigorously enforced.

Sunday, August 22, 2010

Estonia's Long Awaited Recovery May Still Be Delayed Yet Awhile

In a recent FT Op-ed, entitled "Estonia’s recovery defies economists and academics", columnist John Dizard argued that "the “internal devaluation” policy, which means cuts in nominal costs such as wages and rents, was very hard on the population, but appears to have worked ahead of even the Estonian government’s schedule".

But as I said to John in a very enjoyable phone conversation I had with him before he wrote the piece (where he was kind enough to descibe me as a "freelance economist", one who doesn't have to answer to a boss before expressing an opinion), perhaps we should just hold on a minute before jumping to too many conclusions, since things are still far from clear. So let's take a look.

As John points out, many macro economists, among them me myself (here, and here, and here) and Paul Krugman (here) have been arguing that if the Baltic countries stick to their policy of having a fixed exchange rate with the euro, they face a long period of low growth and serious internal deflation. At the start of this debate, I pointed out that the impact of price deflation on the bank loan books would be just the same with or without devaluation: not so, said Krugman (and he was right), the impact is worse, since even the Kroon or Lati denominated loans (which in truth are quite few) are affected.

John however, does not agree, since, he tells us, the country is "stubbornly failing to comply with the predictions of what are called the 'third generation models' for currency crises" and "is already seeing a resumption of growth and a fall in its real cost of capital".

Well, as I told John at the time, the Estonian case is a complex one, since in a country with only just over a million people a myriad of special case factors can be at work, confounding results. But still, the idea is abroad that Estonia is a kind of "black swan", a data point which tends to suggest that conventional macro economic wisdom is somehow flawed. So just how valid is this view. Let's take a look at some data.

In the first place, John is undoubtedly right, economic activity has revived (slightly) in Estonia. In Q2 2010 the economy grew by a seasonally adjusted 2%, following an equivalent contraction in Q1 and growth of 2.6% in Q4 2010 (yes these are quarterly, not annual, numbers).


So the first thing to say is that if these numbers are truly well adjusted seasonally (which make be hard given the boom bust background, and the amplitude of the movement in the data) what we have is a lot of volatility out there. And in the second place, we could well ask ourselves to what extent it is valid to use that so-oft maligned expression "recovery" at this point in the Estonian context. If we look at the GDP volume index (which I have put in 4 quarter moving average format), you have to look very hard indeed (go on, squint a bit more) to actually see the uptick.


I tell you what, I'll do you all a favour, and shorten the time series and change the scale.


Well, that's a bit clearer, isn't it. I think what you can say looking at this chart is that the Estonian economy has been stabilised (no mean feat that, with an economy in freefall), but what happens next, well that, it seems to me, you can't discern from looking at the chart. To decide on that, I think, you will probably need to go back to the initial assessment you had of the problem. If, like John, you believed that what the Estonians were trying was doable, then you will probably draw the conclusion that what comes next will (eventually) be a recovery. If, like me, you had severe doubts from the outset that this was doable, then you will probably imagine the Estonians are now in for a long period of slow, "L shaped" semi-recovery, with a lot of pain still to come, further down the road. But as I say, all of these expectations probably depend on your initial theoretical assumptions (more on this later), and in that sense nothing has fundamentally changed.


That being said, there are some things that have improved in recent months. Retail sales for example.


And then there is industrial output, which is up sharply. It even almost looks like the fist leg of one of those proverbial "Vs".


And part of the reason for this improvement in output has been the recent improvement in demand for Estonian exports.


But before we get too excited about all this, we should remember that Estonia still has a goods trade deficit. That is, on balance, the net goods trade is a drag on GDP.


The problem is that the part of Estonian industry which was internationally competitive before the bust still is, but that this part is not large enough to drive the whole economy, now that the economy is export dependent. It just doesn't have a big enough share in GDP to carry the whole economy. As the Estonian statistics office put it: "GDP growth in the 2nd quarter was supported by the industrial sector exports. Due to a small domestic demand, the sales of manufacturing production on the domestic market were in downtrend. In construction, the output of which is mainly targeted at the domestic market, the generated value added showed a continuous decreasing trend".

This is what I had always expected would be the case.

It should be noted that Estonia runs a substantial services surplus, which at the present time easily cancels out the goods trade deficit. As a result, and this IS the good news, Estonia now runs a current account surplus. Which means that each month now, instead of getting more into debt, the country is steadily paying down its international liabilities. And this is important, since as John points out, Estonia is considerably less indebted externally than many other of Europe's peripheral economies, with net external debt according to IMF data only being some 30% of GDP.


But nonetheless, achieving this positive situation still has a price, and that price is that the economy is being forced to operate at well below capacity level, and the clearest indication of this is the very high continuing level of unemployment. In fact, I think John got interested in his story when he read this report, that the registered unemployment rate in Estonia fell to 12% in mid-July. Since he was aware that first quarter unemployment was somewhere around 19%, this seemed to him like a dramatic drop. But there is a confusion here, since we are dealing with two different measures of unemployment, one of them people who sign at labour exchanges to register as unemployed (and may do so because they have entitlement to unemployment benefit), and those assumed to be really unemployed when measured using ILO compatible (and EU harmonised) quarterly labour force surveys, and as this article points out, according to the latest of these surveys (April - June) there were still 128,000 unemployed, or 18.6 percent of the workforce out of work in June.


Of course, interpreting such data presents its own problems, and the issue is a complicated one, since in the first place there seems to be a large shadow economy in Estonia. According to Professor Friedrich Schneider of Austria's Linz University, based on a study that covered 37 countries, Estonia had the second largest proportion of GDP in the informal economy, with some 40% not paying tax. Top of the list was Latvia, with shadow economy accounting for 42% of the country's GDP, then came Estonia, Bulgaria, Turkey and Greece. So of course, not all those who are not signing the registers are necessarily unemployed, or in the country even, but still people are dropping out of the statistical system, according to the Estonian Health Insurance Fund some 20,000 less people are registered for health cover today than there were in March 2008. At the very least we can assume these people are not working in the formal economy or registering for welfare benefits. Whether they are working in the informal one, or working abroad, we really have no idea.

Be that as it may, according to the Estonian Statistics Office, in the 2nd quarter of 2010 the estimated number of unemployed in Estonia was 128,000 and the unemployment rate was a - seasonally not adjusted - 18.6%. So unemployment did decrease in the quarter for the first time in nearly two years, but by 1.2% (from 19.8% in Q1), and not by the rather large amount it might appear from the labour exchange registration data.

And if you go to the details of the stats office report the situation is more complex than it seems at first sight, since while the number of new unemployed has been declining, long-term unemployment continues to grow. In the 2nd quarter, 58,000 unemployed persons had been looking for a job for one year or more (long-term unemployed), of whom 19,000 had been looking for a job for two years or more (very long-term unemployed). The share of long-term unemployed among total unemployed increased to 46%, while the share of very long-term unemployed rose to 15%. The number of persons who had stopped seeking a job or discouraged persons was also larger in the 2nd quarter than in the 1st (9,000 and 7,000 respectively).

On the other hand the estimated number of employed persons was 559,000, which was up by 5,000 (0.9%) over the previous quarter. According to the statistics office, "employment increased due to seasonal and other temporary jobs typical of the 2nd quarter". Nonetheless there was employment growth, so we should be thankful for any mercy, however small. What remains to be seen is whether this improvement in employment is sustainable as Europe's economies slow going into the second half of the year.

A further bone of contention between the parties evidently concerns the so-called “internal devaluation” policy being applied by the Estonian government. As John Dizzard explains such a policy "means cuts in nominal costs such as wages and rents, (and) was very hard on the population, but appears to have worked ahead of even the Estonian government’s schedule".

When we come to scrutinise the actual data however, the fall in hourly wages has hardly been dramatic, and they have now fallen about 7% from their peak at the end of 2008. But it should be remembered in 2008 they were up by around 7%, so they are now at about the same level as they were in January 2008, following increases of 17.5% in 2006 and 20% in 2007 - rates of increase which ultimately lead to the consumption bust which followed them, and clearly not sustainable in the longer term. So, unfortunately it is just not the case that Estonia has had a very harsh policy of wage cost reduction implemented. Living standards have fallen sharply, due to the reduced hours worked, and the rapid rise in unemployment - ie due to the recession - but that is not the same thing at all as recovering lost competitiveness.


The Real Effective Exchange Rate data on all this is very clear. Up to 2005 the rise in living standards was more or less in line with sustainable economic growth. From 2006 onwards things really got out of hand, and to date only a very small part of the competitiveness loss has been clawed back.


This intrepretation is confirmed by an inspection of the CPI data, which after 9 months of registering mild interannual deflation is now back in positive territory, and more or less a full percentage point above the Eurozone average, which for a country which is supposed to be in the throes of a substantial "internal devaluation" is pretty incredible, and could be seen as another example of someone or other falling asleep at the wheel, after passing the finishing line for Eurozone membership perhaps.


John Dizzard argues that the Estonians are in position for a relatively rapid recovery (this part I don't see at all, anywhere in the data) because they started out with much less state and private debt than the others. This latter point is certainly true, but we should not miss the fact that while Estonia's state debt is very, very small, private sector debt (at around 100% of GDP, between households and corporates) is not so small, and indeed will continue to exert a significant downward pressure on credit growth for some time to come.


Now one of the points raised by John which does have a certain validity is that of lower capital costs. Given the existence of significant quantities of land and warehouse and factory accommodation which are now surplus to requirement due to the "downsizing" which has been going on (creative destruction) employers do now have access to cheaper premisses, and this can offer them lower unit costs for a given level of technology and output. The key point to get here is where the demand is going to come from, and then we are still back with the same issue: exports.

More than the internal devaluation itself, Estonia is benefitting from the decision to grant the country Euro membership. As a result the cost of servicing oustanding debt has falling, as have credit default swap spreads. John quotes one large shareholder in several Estonian companies as saying, “At the beginning of 2009, the banks were offering our companies loans at 600 to 700 basis points above six-month euribor [the euro base rate]. That’s if the money was available at all; most of the time they were cutting lines. Now the banks are offering the same companies increased lines at 100 to 300 basis points over euribor.”

But if we come to look at the impact of this cheap credit, we will see that, as in other economies where private demand is highly leveraged (the UK, the US, Spain), the uptake on all this ultra cheap credit has not exactly been massive. In both cases the interannual rates of credit growth are still negative, which is one of the key reasons domestic demand remains so weak.


Although we can see the first timid signs of recovery in the housing market, both in terms of sales volume and in terms of prices, but at this point they are just this, timid signs.


So to go back to where we started, and John Dizzard's claim that "Estonia’s recovery defies economists and academics", I would say that rather than economists and academics (or even academic economists) who Estonia's current situation does really defy is the group of people over at the ECB governing council headed by Jürgen Stark, since, as I reported back in April, consensus thinking at the ECB was that Estonia was not coming into the common currency , due to ongoing concerns about sustainability and competitiveness issues.

But that was April, and then came May, when the ECB was forced to do a "U turn" by the crushing pressure of the European Sovereign Debt Crisis, so all these (valid in my view) concerns where simply brushed aside. And anyway, how could anyone argue for keeping Estonia out on these grounds, when you have countries like Spain and Portugal on the inside. Either internal devaluation works, or....

So maybe it was better for them to stay with the line that internal devaluation works, and whether they are right or not is what we are all about to get to see. As I said at that start the post, in this case as in so many others, beauty is in the eye of the beholder. If you believe in the neo classical (academic) theory of "steady state" growth - and the guy over at Swedbank that John cites who is forecasting that Estonian gross domestic product will grow at a 4.5 per cent rate next year evidently does - then naturally Estonia's economy has only been temporarily knocked off its path by this whole unfortnate incident, and will soon be back in it habitual orbit.

If, however, like me you suspect that neo-classical steady state growth is some sort of metaphysical hocus pocus (or what they call a "necessary assumption to get the argument going") with little empirical support, then you will not be terribly convinced by all those numbers blindly and slavishly churned out by the current generation of models, and will look more to the facts on the ground. In particular, when we come to the neo classical growth theories which normally underpin the sort of optimistic analyses we see of the Estonia situation (yes John, there are academic economists on both sides), I tend to think these are flawed due to some initial erroneous assumtions Solow himself made about the impact of population dynamics on growth (see this extended argument here), and I think it is important to remember here that Estonia, along with Hungary, Latvia and Bulgaria, is one of the countries on Europe's Eastern flank where population as well as ageing is actually falling. So I suggest you treat any analysis which talks about a steady recovery in internal demand but does not explicitly explain how this point has been taken into account....... well I suggest you treat it with more than a pinch of salt.


And then, of course, there is the idea of "export dependence" and ageing, and what this all means for the future trajectory of the Estonian economy. This argument, which Claus Vistesen and I have been advancing for some years now (and is one of the reasons so many of those famous "predictions" turn out to be valid), shot to the financial headlines recently when Dominic Wilson and Swarnali Ahmed of Goldman Sachs drew the obvious to everyone's attention - namely that balance of payments current accounts are significantly driven by life cycle savings. Maybe you can argue about the validity of the age group classifiaction they use (an empirical calibration issue), but the obvious is obvious: the relative proportions of different age groups across different countries goes a long way to explaining the pattern of global savings and capital flows. And as Claus Vistesen illustrated in the chart below, this helps us understand how societies (Germany, Japan...) become increasingly export dependent as they age.


So, as I said earlier, your expectations about the future outlook for the Estonian economy will largely depend on the initial theoretical assumptions you make at the outset. If you assume that neo classical steady state growth really exists, and that all this stuff about ageing, capital flows and export dependence is exaggerated, then you will see the recovery coming in the here and now, and if you don't.........